Luottotietolaki muuttui kahdessa vaiheessa. Ensimmäiset muutokset astuivat voimaan 1.6.2022. Muutokset lain 18 §:ään ja 28 §:ään tulivat voimaan kuusi kuukautta myöhemmin kuin muut lainkohdat (eli 1.12.2022).
Näkyvimmät muutokset tapahtuivat toisessa vaiheessa (1.12.2022). Silloin astui voimaan velan maksun rekisteröinnin vaikutus maksuhäiriön rekisteröintiaikaan (maksuhäiriö poistuu rekisteristä 30 pv päästä velan maksun rekisteröinnistä luottotietorekisteriin). Myös maksuhäiriön rekisteröintiaikojen pidennys- sekä lyhennysvaikutuksen poistuivat.
Maksuhäiriöiden tallennusaika on jatkossa 3 vuotta, lukuun ottamatta kulutusluottohäiriömerkintöjä (OSP ja LKP), joiden rekisteröintiaika on 2 vuotta. Aiemmin käytössä olleet pidennys- ja lyhennysvaikutukset poistuvat, eikä uusi maksuhäiriö aiheuta enää jatkossa vanhan maksuhäiriömerkinnän pidentymistä.
Jos maksuhäiriön aiheuttanut velka maksetaan ja maksuhäiriöön rekisteröidään tieto velan maksamisesta (eli ns. Ref-merkintä), maksuhäiriömerkintä poistetaan 30 pv kuluttua siitä, kun tieto velan maksusta on rekisteröity luottotietorekisteriin. Tämä koskee myös ennen lakimuutosta tulleita maksuhäiriöitä, joista löytyy tieto maksusta.
Tiedon voi toimittaa velkoja tai velallinen itse. Käsittelyn nopeuttamiseksi toivomme, että tieto velan maksusta toimitetaan velkojalta luottotietoyhtiölle.
Tarkasta kuitenkin ensin, onko sinulla voimassa olevia maksuhäiriömerkintöjä. Tarkastuksen voit tehdä täältä.
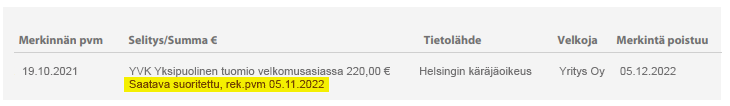
Jos näet maksuhäiriömerkintöjä raportilla, katso ensin löytyykö maksuhäiriöstä "Saatava suoritettu" -tietoa (eli ns. ref-merkintä). Se tarkoittaa, että velka on jo maksettu ja tieto maksusta on kirjattu maksuhäiriöön.
Jos maksuhäiriössä ei näy "Saatava suoritettu" -maksutietoa, lue tämän sivun ylälaidasta tarkemmat ohjeet kohdasta "Maksutiedon lisääminen maksuhäiriömerkintään".
Asiakastieto kirjaa tiedon maksusta (eli ns. ref-merkinnän) vasta sen jälkeen, kun velkoja on ilmoittanut saatavan suoritetuksi (eli velan maksetuksi). Eli sovi maksuhäiriöön liittyvän velan maksusta velkojan kanssa saadaksesi siihen tiedon maksusta.
Nämä ovat kaksi eri lakimuutosta, ja on hyvä erottaa ne toisistaan.
Positiivista luottotietorekisteriä koskeva muutos astui voimaan 1.8.2022. Positiiviseen luottotietorekisteriin tullaan keräämään tietoa luotonantajien myöntämistä luotoista ja sen tarkoituksena on esimerkiksi torjua ylivelkaantumista. Vaikka positiivinen luottotietorekisteri astui voimaan 1.8.2022, se on tarkoitus ottaa käyttöön vasta keväällä 2024. Positiivisen luottotietorekisterin rekisterinpitäjänä toimii Verohallinto.
Nykyistä luottotietolakia (joka käsittelee negatiivista luottotietoa eli maksuhäiriöitä) koskevat muutokset astuivat voimaan 1.6.2022 ja 1.12.2022. Näkyvimmät muutokset tapahtuivat toisessa vaiheessa (1.12.2022). Silloin astui voimaan velan maksun rekisteröinnin vaikutus maksuhäiriön rekisteröintiaikaan (maksuhäiriö poistuu rekisteristä 30 pv päästä velan maksun rekisteröinnistä luottotietorekisteriin). Tämän rekisterin toisena rekisterinpitäjänä toimii Suomen Asiakastieto.
Laskun eräpäivän jälkeen 1-2 maksumuistutusta
Perintävaiheessa 1-2 maksuvaatimusta eli perintäkirjettä
Perinnän jälkeiset vaiheet velasta riippuen (A, B tai C)
Useimmat velat
A
Haaste
Ulosottokelpoiset velat
(esim. julkishallinnon velat)
B
Ulosotto
Maksukehotus
Useimmat kulutusluotot
C
Suoraan perinnästä maksuhäiriöksi, jos velka yli 60 pv myöhässä
Käräjäoikeuden tuomio
Varattomaksi toteaminen ulosotossa
Ensirekisteröintikirje
Suomen Asiakastieto lähettää luottotietorekisteriin kirjatusta ensimmäisestä maksuhäiriöstä kirjeen
Jos maksusi alkavat viivästymään, suosittelemme että olet mahdollisimman nopeasti yhteydessä velkojaan. Useimmissa tapauksissa on mahdollista sopia maksusuunnitelmasta, jolla tilanteen saa hallintaan.
Yllä oleva kaavio havainnollistaa yleisimmät perinnän etenemisen ja maksuhäiriön muodostumisen vaiheet.
366 600 suomalaisella on maksuhäiriö
Maksuhäiriö on vakava asia ja se vaikuttaa moniin arjen perusasioihin. Maksuhäiriön tarkoitus on kuitenkin pysäyttää velkaantumiskierre. Omatieto-palvelusta voit kerran vuodessa tarkastaa omat luottotietosi maksutta.
You can get a payment default, if a payment related to a claim or service has been unpaid long enough. In consumer credit defaults, the payment must be over 60 days overdue. If the payment for a debt is claimed at the District Court, the court decision generates the payment default entry. In addition, a payment default entry can be filed by the enforcement authority.
Credit information is used in different types of decision-making.
For example, credit information is used when granting a monetary credit, opening a telephone subscription, selling on invoice, renting an apartment, making insurance contracts and opening accounts with credit. In many cases, a credit information entry may be an obstacle, or it may essentially complicate the making of many contracts.
You can buy an extract of your own credit information from our service. Please, acquire the extract of your own credit information here.
When you wish to regularly monitor your credit information and secure your information against identity theft, you should get Tietovahti service. You can retrieve reports from the service always when you need them. The service is in Finnish but it contains the English credit report. Get to know the service here.
You can check your credit information via Omatieto service once in 12 months. If you need to check the information again, please contact our customer service. More information (Finnish only).
You can inspect your own credit information by using the statutory inspection right. You can check your credit information via Omatieto service once in 12 months.
When you have paid off the debt associated with the payment default, ask the creditor to submit a payment notification to Asiakastieto. This is the primary and usually the fastest way to get payment information linked to the payment default entry.
If the payment concerns an enforcement entry, please contact the creditor who placed the entry. If you have paid off a debt to National Enforcement Authority Finland, please ask the enforcement authority to notify us of the payment in order to speed up the processing. You can submit the request through the Enforcement Authority's online service or by email at (ulosotto.uo@oikeus.fi). The message must include the person's full name and date of birth. Enforcement entries are deleted in the same way as other payment default entries.
If the creditor is unable to provide Asiakastieto with payment information, you can also provide it yourself. The notification of payment information must include sufficient proof of payment. Such proof is, for example, a written notification received from the creditor about the payment of the debt or an identifying receipt (to whom, what amount, reference information) for the payment.
If you paid the debt through the Enforcement Authority, you may provide the "Debtor's Enforcement Matters" printout, which is available through the Enforcement Authority's online service (ulosottolaitos.fi). Please note that if you submit the certificate yourself, processing may take longer, as we must separately verify its authenticity with the Enforcement Authority.
It is recommended to send your payment details encrypted, and this can be done using Asiakastieto's secured email: go to: https://mail.asiakastieto.fi and send message to the address maksutiedot@asiakastieto.fi
When the credit information agency has received the payment information, the payment default entry will be deleted after 30 days, unless it is an UMS or UMP, which will be deleted immediately after the payment is registered.
If a debt related to an UMS or UMV entry expires and Asiakastieto receives reliable information about it (usually directly from the Enforcement Authority), the UMS entry will be deleted immediately and the UMV entry after 30 days.
If you have paid a debt related to a payment default in its entirety, this can be reported to Asiakastieto. Information on the settlement of the payment (ref entry) is linked to the payment default entry. The settlement of the payment must be notified in writing. A reliable statement of the settling of the payment must be attached to the notice; for example, a certification provided by the creditor or some other reliable statement. It is recommended to send the message encrypted, and this can be done using our secured email: go to https://mail.asiakastieto.fi and send message to the address maksutiedot@asiakastieto.fi
The ref data is based on the data subjects request. The processing time for payment information (ref data) is approximately two business days. Ref data are processed in the order of arrival.
By inspecting your credit information, you get to know what information the credit grantor sees when granting a credit. This way you can better prepare yourself for credit applications or credit negotiations. Even though errors in credit information are scarce, by inspecting your own information you can make sure that the information is correct. If a person has credit information entries, by inspecting your own information you will also find out who has requested your information and when. This way you can make sure that the credit information has been disclosed only for appropriate purposes. After the inspection of own information, you can also plan how to improve the credit information by linking a ref entry to the payment defaults, indicating that the claims behind the entry have been paid.
You can get support for financial problems, among others, from the financial and debt counselling at legal aid offices and the Guarantee Foundation. Please, find more information on these organisations below.
Financial and debt counselling at legal aid offices
Financial and debt counselling is a statutory service, which is free of charge to the customers. Counselling is organised by legal aid offices. The website of the financial and debt counselling at [https://oikeus.fi/talousjavelkaneuvonta/en/index.html] provides ample instructions on the balancing of the financial situation. At the same address, you can also find the contact information for the financial and debt counselling in your own area.
Takuusäätiö
Takuusäätiö is a national organisation in the social field which assists private persons struggling with a financial crisis in solving their debt and payment problems.
Takuusäätiö offers counselling by phone and gives instructions for solving debt problems. The foundation grants e.g. guarantees for bank loans, with which debts can be combined in a situation of over indebtedness and organises support person activity to persons who find themselves in a financial crisis. You can call the Takuusäätiö's Debt Line for free in Finland and discuss the financial troubles concerning you or your family members. The Debt Line operates at the number 0800 9 8009, Mon-Fri, 10 a.m. - 2 p.m. Alternatively, you can contact them through their chat. More information and instructions are found on Takuusäätiö's website www.takuusaatio.fi.
If you detect an error in the registration of the payment default, you have to contact the creditor. The request for removal has to come from the creditor.
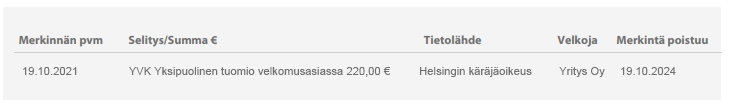
Jos sinulla on maksuhäiriömerkintöjä, katso onko merkinnän yhteydessä Saatava suoritettu –tieto (eli maksutieto eli ns. ref-merkintä).
Jos ref-merkintä löytyy, sinun ei tarvitse tehdä mitään. Maksuhäiriömerkintä poistuu 30 pv kuluttua maksutiedon rekisteröintipäivämäärästä.
❌
Jos ref-merkintä puuttuu, ole yhteydessä raportilla näkyvään maksuhäiriömerkinnän velkojaan tai tietolähteeseen selvittääksesi kenelle velka tulee maksaa.
➜
Maksa maksuhäiriön aiheuttanut saatava velkojalta saamiesi ohjeiden mukaisesti.
A. Pyydä velkojaa toimittamaan maksutieto Asiakastiedolle
Ensisijainen, varmin ja yleensä nopein tapa saada maksutieto maksuhäiriömerkintään
Jos maksoit velan Ulosottoon, käsittelyn nopeuttamiseksi pyydä Ulosottolaitosta ilmoittamaan maksutieto meille. Voit tehdä pyynnön Ulosoton sähköisessä asiointipalvelussa tai sähköpostitse osoitteeseen ulosotto.uo(at)oikeus.fi.
B. Toimita tiedot itse
Jos velkoja ei pysty toimittamaan maksutietoa Asiakastiedolle, voit toimittaa sen itse.
Pyydä velkojalta kirjallinen tosite saatavan maksusta. Tosite voi olla maksukuitti tai saldotodistus, jolla velkasi todetaan tulleen maksetuksi.
Jos maksoit velan Ulosottoon, voit toimittaa Velallisen ulosottoasiat -todistuksen, jonka saat Ulosottolaitoksen sähköisestä asiointipalvelusta (ulosottolaitos.fi).Huomioithan, että jos toimitat todistuksen itse, käsittely voi kestää pidempään, sillä joudumme varmentamaan todistuksen aitouden erikseen Ulosottolaitokselta.
Varmista, että tositteesi sisältää seuraavat tiedot:
Saldotodistus, jossa todetaan merkintäsi aiheuttaneen velan tulleen maksetuksi, tai todetaan että sinulla ei ole avointa saatavaa.
Maksukuitti, josta käy ilmi velkojan ja velallisen nimet, maksettu summa, maksupäivä, arkistointitunnus sekä viitenumero (maksuhäiriössä oleva asianumero tai diaarinumero). Mukaan voi liittää kopion laskusta, josta käy ilmi em. viitenumero. Maksuhäiriön koodi ja maksuhäiriön rekisteröimispäivämäärä ovat hyviä lisätietoja maksunsuorituksen kohdistamiseen, mutta eivät pakollisia.
Uutta!
Voit nyt toimittaa tositteen maksamastasi velasta Omatieto-palvelussa. Huomaathan, että maksutiedon toimittaminen Omatieto-palvelussa on mahdollista ainoastaan seuraaville maksuhäiriömerkinnöille:
YVK, Yksipuolinen tuomio velkomusasiassa
UMV, Ulosottomenettelyssä todettu varattomuus tai muu este
UMS, Ulosottomenettelyssä todettu varattomuus tai muu este
Sinut ohjataan vahvan tunnistautumisen jälkeen palveluun.
Mikäli kyseessä on jokin muu maksuhäiriömerkintä kuin yllä mainitut, voit toimittaa tositteen turvallisen sähköpostiohjelman kautta. Mene osoitteeseen https://mail.asiakastieto.fi ja lähetä viesti osoitteeseen: maksutiedot@asiakastieto.fi
Maksutietojen käsittelyaika on arviolta 2 työpäivää. Edellä mainittu käsittelyaika koskee ainoastaan rekisteröidyn itsensä Suomen Asiakastieto Oy:lle suoraan toimittamia maksutietoja, emmekä voi vaikuttaa tätä pidempiin maksutietojen kirjautumisviiveisiin, jotka aiheutuvat Suomen Asiakastiedolle maksutietoja toimittavien muiden tahojen omista käsittelyajoista.
Kun maksutieto/ref on kirjattu maksuhäiriöön, maksuhäiriömerkinnässä lukee ”Saatava suoritettu” (Selitys/Summa € -kentässä) sekä maksutiedon rekisteröintipäivämäärän. Maksuhäiriömerkinnän aiheuttanut saatava on maksettu ja maksutieto on kirjattu.
Nyt asia on kunnossa. Maksuhäiriömerkintä poistuu 30 pv kuluttua maksutiedon rekisteröintipäivämäärästä.
Luottotietojen muutoksia seuraat helpoiten Luottotietoni 24/7 -palvelulla, jolla näet koko ajan ajantasaisen tilanteen luottotiedoistasi
ja maksutiedon kirjautumisesta.